
Insights · LinkedIn
Your business insurance was written for the business you had when you bought it.
Your business insurance was written for the business you had when you bought it.
Since then, maybe you added a second van, bought new equipment, let people work from home, or started taking bigger jobs. The policy renews on its own, and most owners don't read past the price.
The gaps usually show up on the worst possible day: after a theft, a fire, or a fake invoice gets paid.
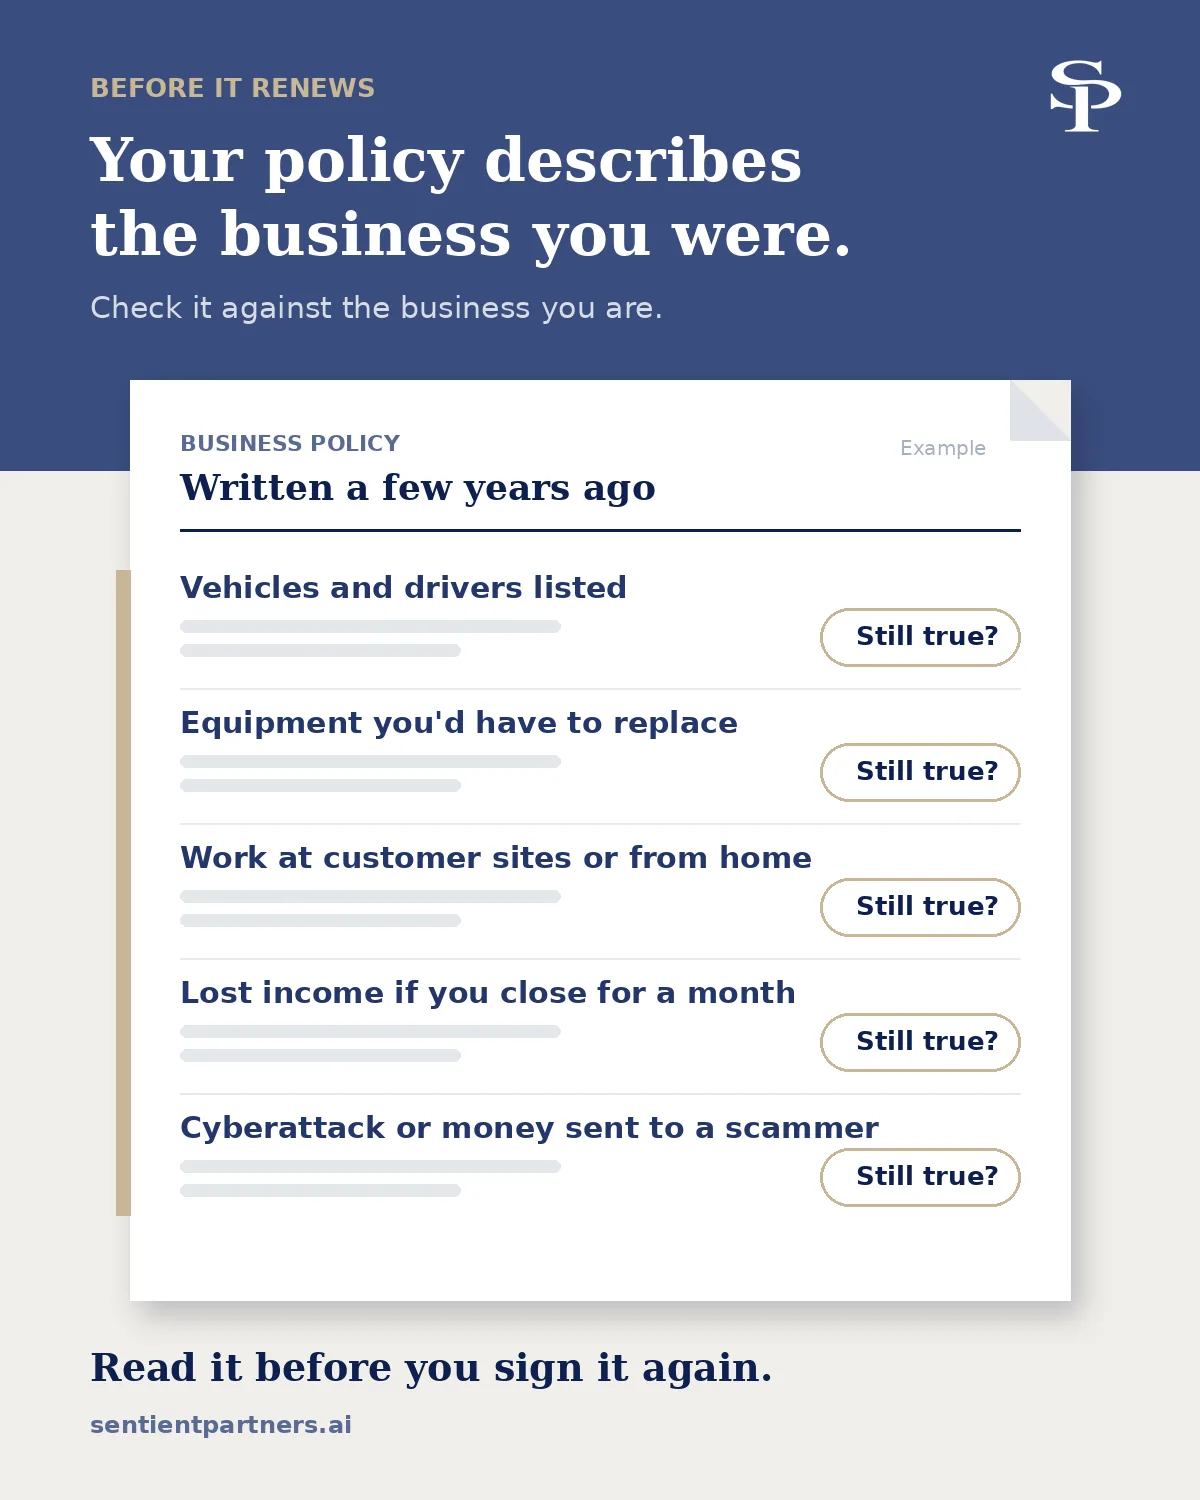
Before your next renewal, pull out the policy and check it against today: Are all your vehicles and drivers listed? Does the equipment coverage match what you'd actually have to replace? Does it cover work at customer sites or from home? If you had to close for a month, would it cover lost income? Does it cover a cyberattack or money sent to a scammer, or is that excluded?
Then call your agent with the list. Ask what changed, what's excluded, and what it would cost to close the gaps. You may decide some gaps are fine to carry. At least it'll be a decision instead of a surprise.
Sentient Partners: your local business and technology partner. sentientpartners.ai